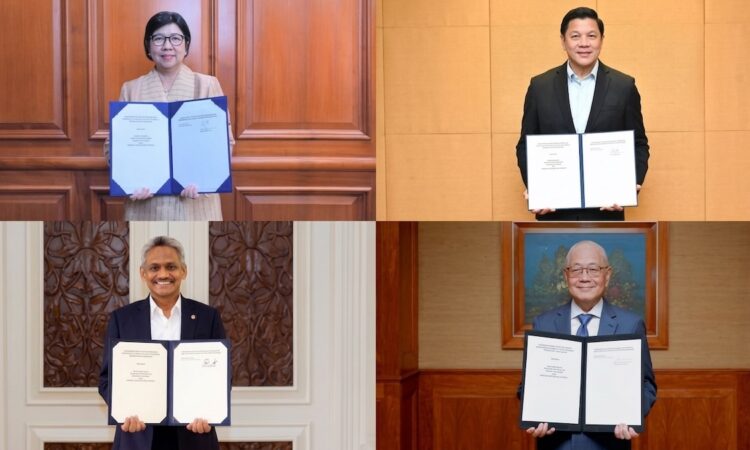
Key Takeaways:
- A stronger U.S. dollar would raise import costs and foreign-currency burdens for ASEAN economies, reinforcing the value of the November 13, 2026 local-currency transaction (LCT) framework signed by the central banks of Indonesia, Malaysia, Thailand and the Philippines.
- The LCT arrangement aims to cut double-conversion costs and exchange-rate risk on regional trade and investment by enabling direct local-currency settlement, functioning as risk diversification rather than de-dollarization, as dollar liquidity remains essential for global transactions.
- With ASEAN’s $4.26 trillion economy and rising intra-regional production networks, success depends on expanding dealer networks, hedging tools, SME access and links to cross-border QR payments so the framework supports integrated supply chains rather than remaining limited to large corporates.
What would happen if the US dollar strengthened again amid rising trade and investment across Southeast Asia? A stronger dollar is fundamentally part of the normal dynamics of global financial markets. For ASEAN economies, however, such a shift can increase import costs, raise the burden of foreign-currency obligations, and require businesses to spend more on managing exchange-rate risks. Its effects can also reach transactions between regional economies that continue to use the dollar as an intermediary currency.
The dollar’s position as the world’s leading currency has provided the liquidity, certainty, and common settlement standards required for international trade. Yet, as economic ties within Southeast Asia expand, the region needs more diverse settlement options. An Indonesian company purchasing goods from Malaysia, for example, should not always have to convert rupiah into dollars before the payment is converted into ringgit, particularly when an efficient and secure direct-settlement mechanism is available.
It is in this context that the memorandum of understanding signed by Bank Indonesia, Bank Negara Malaysia, the Bank of Thailand, and the Bangko Sentral ng Pilipinas on November 13, 2026, becomes particularly relevant. The framework promotes the use of local currencies in eligible bilateral transactions, including trade and investment. It also replaces the earlier framework agreed by Indonesia, Malaysia, and Thailand in August 2023. Its purpose is to improve settlement efficiency, reduce conversion costs, widen businesses’ options for managing exchange-rate risk, and strengthen regional financial cooperation and economic resilience.
Not De-Dollarization, but Risk Diversification
The expansion of local-currency transactions is sometimes interpreted as another step toward de-dollarization. That interpretation is too simplistic. The dollar remains essential to global trade, commodity pricing, international financing, and reserve management. Its deep liquidity and widespread acceptance cannot easily be replicated by a regional arrangement.
The more realistic function of the Local Currency Transaction, or LCT, framework is to reduce unnecessary reliance on an intermediary currency when transactions occur between neighboring economies. Converting rupiah into dollars and then dollars into ringgit can expose a business to two exchange-rate spreads. Direct settlement can potentially remove one layer of conversion, lower costs, and provide greater certainty over the amount ultimately received.
This is financial diversification rather than monetary confrontation. ASEAN economies can continue using the dollar for global financing and external trade while expanding local-currency settlement for suitable regional transactions. LCT will not isolate Southeast Asia from changes in US interest rates, shifts in investor sentiment, or global financial volatility. It can, however, reduce the number of transactions exposed to multiple conversions and offer businesses an additional settlement route when external conditions become less favorable.
Demand for such alternatives is already growing. LCT transactions involving Indonesia reached the equivalent of $14.1 billion by July 2025, up 112 percent from $6.7 billion in the corresponding period of 2024. In only seven months, the total had reached around 87 percent of the $16.28 billion recorded throughout 2024. Average monthly users also increased from 5,020 in 2024 to 7,568 in 2025.
Matching Payment Infrastructure with ASEAN’s Economic Scale
The economic case becomes clearer when measured against ASEAN’s size. In 2025, the region had approximately 693.2 million people and a combined gross domestic product of $4.26 trillion. Its economy grew by 4.9 percent, while total merchandise trade reached $4.37 trillion, comprising $2.23 trillion in exports and $2.14 trillion in imports. Trade in services added another $1.40 trillion.
Investment is also deepening regional production networks. ASEAN received around $245.7 billion in inward foreign direct investment in 2025, up from $223.1 billion in 2024. These flows support industries in which production is distributed across several countries, including electronics, semiconductors, automotive manufacturing, digital services, and renewable energy.
This creates a mismatch between ASEAN’s increasingly integrated real economy and its still-fragmented financial infrastructure. A product assembled in Thailand may incorporate Indonesian raw materials, Malaysian electronic components, and Philippine business services. If payments at each stage pass through a third currency, conversion costs and exchange-rate exposure can accumulate along the supply chain.
The participating central banks must therefore expand the network of appointed cross-currency dealers, harmonize documentation, improve price transparency, and support deeper forward and swap markets. Without effective hedging instruments, businesses may save on conversion costs but remain vulnerable to currency movements between signing a contract and receiving payment.
From Central Bank Agreement to Regional Infrastructure
Small and medium-sized enterprises require particular attention. Large companies generally possess treasury expertise and established banking relationships, while smaller exporters may be deterred by documentation requirements, minimum transaction thresholds, or opaque exchange-rate spreads. Banks should provide simpler LCT products with transparent pricing, while central banks should publish comparable information on transaction costs, settlement times, currency pairs, and user composition.
LCT should also be connected with ASEAN’s cross-border QR payments and instant-payment linkages. Combining local-currency settlement with digital payment connectivity could move the framework beyond specialized corporate banking and make it useful for tourism, retail transactions, digital services, and smaller businesses.
This connection offers an important insight: LCT can become more than a currency arrangement. It can serve as regional financial infrastructure supporting ASEAN supply chains. By allowing currency risk to be managed closer to the underlying economic activity, the framework could encourage businesses to source inputs, invest, and form commercial partnerships within the region.
Success should consequently not be measured only by transaction value. More meaningful indicators include narrower currency spreads, faster settlement, wider availability of hedging products, increased SME participation, and a larger share of contracts invoiced in regional currencies. Publishing such indicators would show whether LCT is genuinely improving efficiency or merely transferring costs elsewhere in the financial system. In an increasingly uncertain global environment, greater diversity in currencies, payment channels, and liquidity sources is itself a form of economic resilience.
- The views expressed in this article are solely those of the author and do not necessarily reflect the views of the institution where the author is employed.