Since its spinoff from Murphy Oil (NYSE:MUR) in 2013, Murphy USA (NYSE:MUSA) has been a 14-bagger for investors, generating an annualized total return of 22% over that span.
Despite this stellar run, Murphy USA still trades at a discounted valuation, with an EV/EBITDA (earnings before interest, taxes, depreciation, and amortization) ratio of just 9.5 and a forward price-to-earnings ratio of 14.4. Thanks to this reasonable pricing and the following promising attributes that make Murphy USA a top-tier holding, here’s the case for the company being the smartest dividend stock to buy with $1,000.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
Three reasons Murphy USA could keep beating the market
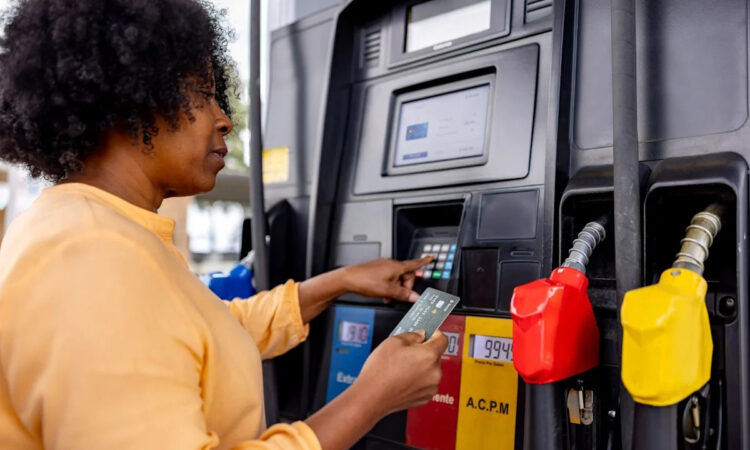
Leading scale, lowest gas prices, and heavy daily traffic: Home to over 1,800 locations across the Southeast and Midwest portions of the U.S., Murphy is the fourth-largest convenience-store chain in the country. This size gives it the scale to offer everyday low gas prices to customers, with fuel commonly sold $0.10 cheaper than its peers.
Thanks to a now-defunct partnership with Walmart (NASDAQ:WMT), most of Murphy’s locations are next to some of the mega-retailer’s stores, drawing heavy daily shopping traffic from customers typically focused on finding the best deals.

Image source: Getty Images.
Massive share buybacks: Powered by its outsize pump traffic, Murphy not only sells tons of gas at a slim profit, but also ample high-margin inside merchandise (snacks, beverages, nicotine, etc.). The steady cash flows from these sales fund the company’s massive stock repurchase program, which has reduced MUSA’s shares outstanding from 37 million to 18 million over the last decade.
A quickly growing dividend: Despite spending heavily on share repurchases, Murphy still has cash left over for quarterly dividend payments. Management started paying a $0.25 quarterly dividend in 2020 and has increased payments to $0.72 as of its last quarter. While the dividend currently yields only 0.54%, it pairs well with the company’s buybacks, as the company can increase payments if the stock ever trades at a higher valuation.
Why now?
Murphy plans to open roughly 50 new stores annually as the industry continues to consolidate, which should reinforce the company’s niche moat and provide ample growth to justify its meager valuation.